
Introduction
After a fall on someone else's property, many people struggle with the same questions: who is responsible, what the claim is worth, and whether the owner’s insurer will take it seriously. A slip and fall settlement is a negotiated payment meant to cover losses caused when a property owner or occupier failed to keep the premises reasonably safe. It is not a court verdict, and it is not automatic just because someone got hurt.
This guide covers falls in stores, restaurants, apartment buildings, workplaces, parking lots, and similar properties across the United States. State law still controls the details. Filing deadlines, comparative fault rules, and what counts as proof of a hazard all differ from state to state.
There is no universal settlement number. A sprained ankle handled with one ER visit settles very differently from a spinal injury that needs surgery.
Injury severity, medical costs, lost income, evidence quality, insurance coverage, and negotiation strategy all shape the result. This guide walks through each factor, with a focus on how Florida law applies.
Key Takeaways
- No reliable "average" settlement exists — facts, injuries, and evidence drive every number
- Proving a claim requires linking a dangerous condition to the owner's failure to act, plus documented damages
- Compensation can include medical bills, lost wages, future losses, and pain and suffering
- Prompt medical care and careful evidence preservation strengthen a claim significantly
- Florida's deadlines and comparative-fault rules should be confirmed with an attorney before accepting any offer
What Is a Slip and Fall Settlement and Why Does It Matter?
A slip and fall settlement resolves a personal injury claim without a trial. Both sides agree on a dollar figure, and the injured person releases their legal claims against the property owner or insurer. That differs from a jury verdict: there's no judge, no formal finding of fault, and no public trial record.
Premises Liability Basics
Most slip and fall claims rest on premises liability law. A property owner, business, landlord, or contractor can be held responsible when:
- A dangerous condition existed on the property
- The owner knew, or reasonably should have known, about it
- The owner failed to fix it or provide adequate warning
- That failure caused an injury
Invitees — customers, tenants, and other lawfully present visitors — get the highest level of legal protection. Property owners must inspect for hazards and warn of known dangers.
What a Settlement Actually Pays For
Compensation typically falls into two categories:
- Economic damages: medical bills, future treatment, lost wages, reduced earning capacity
- Non-economic damages: pain and suffering, emotional distress, disfigurement, loss of enjoyment of life
Your settlement offer and your final payout aren't the same number. Before money reaches your pocket, expect deductions for attorney's fees, case expenses, medical liens, and amounts owed back to health insurers or Medicare.
Settlement vs. Trial
Settling offers certainty and control — you know the number, avoid the cost of litigation, and get paid faster. Trial risks a bigger award but takes longer and carries no guarantee. Most premises liability cases settle long before a jury is involved, which is why understanding the offer, the deductions, and your net recovery matters as much as the headline number.
How Is a Slip and Fall Settlement Determined?
Online payout charts and "average settlement" articles should be treated with skepticism. No state bar association or jury verdict reporter publishes a reliable national average for slip and fall cases, and any figure that claims otherwise can't predict your individual result.
Injury Severity Sets the Floor and Ceiling
A twisted ankle that heals in six weeks settles far differently than a herniated disc requiring surgery. Value hinges on:
- Whether treatment was temporary or created lasting impairment
- Surgical intervention, fractures, or traumatic brain injury
- Spinal injuries, chronic pain, or reduced mobility
- Long-term prognosis and future care needs
Building the Damages File
Every dollar claimed needs documentation behind it. Gaps in this file give insurance adjusters an opening to argue you're overstating your losses.
Core records typically include:
- Medical records and itemized bills
- Pay stubs, tax returns, and employer wage-loss letters
- Expert projections for future care
Adjusters and juries also weigh non-economic harm: pain duration and intensity, sleep disruption, emotional distress, and testimony from you, family members, and treating providers.
Liability and Comparative Fault Change Everything
Strong medical bills mean nothing if you can't prove fault. Florida follows a modified comparative negligence rule: if you're found more than 50% at fault for your own fall, you recover nothing. Below that threshold, your damages simply get reduced by your assigned percentage of fault (Florida Statutes § 768.81).
Example: Imagine a shopper with $80,000 in documented medical bills from a fall near a store entrance. Surveillance shows the spill existed for only 90 seconds before the fall, not long enough to prove the store should have discovered it. Without proof of actual or constructive knowledge, even a strong medical file will not support a settlement near $80,000.
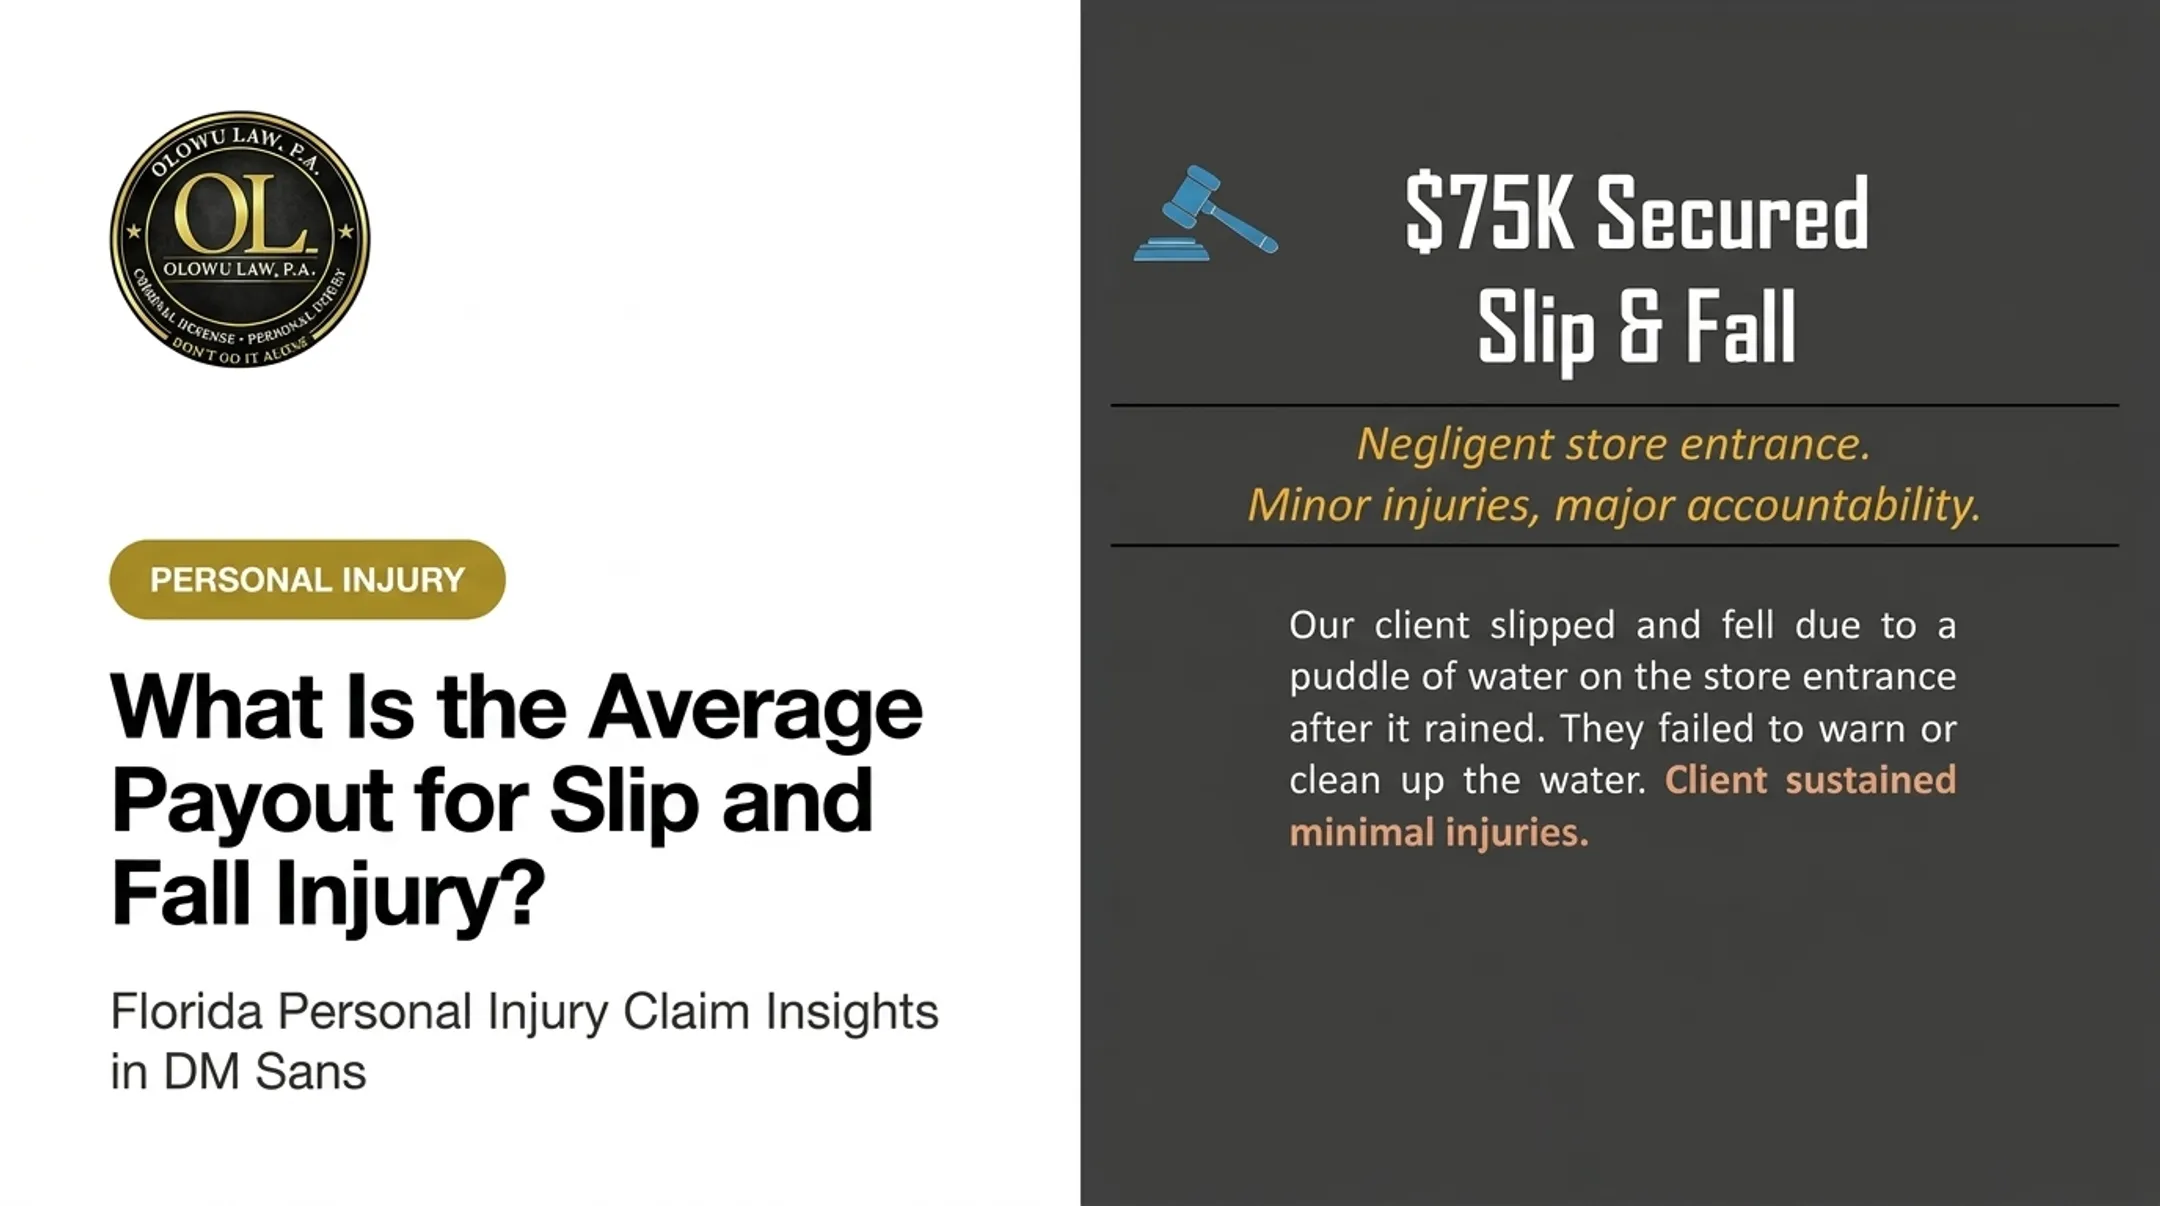
Compare that to a case Olowu Law, P.A. handled, where discovery uncovered surveillance footage and internal records showing a spill had gone unaddressed for an extended period. That evidence turned a $100 initial offer into a $250,000 recovery. The medical bills didn't change between those two outcomes. Proof of the store's knowledge did.

How the Slip and Fall Claim Process Works
A slip and fall claim moves through distinct phases, and each one affects your final settlement amount.
Get medical care and document the scene. See a doctor right away, even if the injury seems minor. Report the fall to a manager or property rep, photograph the hazard, collect witness contacts, and keep the shoes and clothing you wore.
Investigate before evidence disappears. Surveillance footage often gets overwritten within days. Request incident reports, maintenance logs, weather records, and witness statements as early as possible.
Build the demand. Organize liability evidence and calculate documented damages: medical bills, lost wages, projected future costs. Account honestly for any prior or unrelated conditions; insurers will find them anyway.
Negotiate with the adjuster. Adjusters look for reasons to reduce or deny claims: treatment gaps, disputes over notice, or an argument that you were partly at fault. Avoid speculating, exaggerating, giving a recorded statement, or signing a release without understanding exactly what it waives.
Litigate if necessary. If negotiations stall, next steps include mediation, filing suit, discovery, depositions, and possibly trial. Many cases still settle after a lawsuit is filed, sometimes at the last minute.
How Long Does This Take?
Timing depends on your medical recovery, whether liability is disputed, how quickly evidence was preserved, and the insurer's willingness to negotiate in good faith. A straightforward case with clear liability might resolve in months. A contested case that heads into litigation often takes much longer—sometimes well over a year.

Evidence, Eligibility, and State-Specific Rules
The Core Questions Every Claim Must Answer
Before settlement value even enters the conversation, a claim has to answer:
- Were you lawfully on the property?
- Did the owner owe you a duty of care?
- Did a dangerous condition exist?
- Did the owner cause it, or know (or should have known) about it?
- Did that condition cause your injuries, and what damages resulted?
Evidence That Moves a Claim Forward
Useful documentation includes:
- Scene photographs and surveillance footage
- Incident reports and witness contact information
- Maintenance and inspection logs
- Warning signs, or proof none were posted
- Medical records showing how your daily life has changed
Status and Property Type Can Change the Analysis
Not every fall gets treated the same way:
- Trespassers generally receive less protection than invited guests
- Open-and-obvious hazards can complicate a claim but do not automatically defeat it
- Falls on government property often require formal written notice within a much shorter deadline than a standard filing window
- Workplace falls are typically handled under workers' compensation instead of a premises liability claim
Florida's Specific Rules
Florida law changed in 2023. House Bill 837 cut the statute of limitations for negligence claims, including most slip and fall cases, from four years down to two years for cases arising on or after March 24, 2023 (Florida Senate, HB 837 Bill Summary). Missing this window generally bars the claim entirely, no matter how strong the evidence is.
Florida also applies a specific standard for falls caused by a "transitory foreign substance" in a business, like a spill. You generally must show the business had actual knowledge of the hazard, or that it existed long enough — or occurred with enough regularity — that the business should have discovered it.

Before Your Consultation
Gather what you can, but don't delay reaching out just because your file feels incomplete:
- Accident or incident reports
- Photos of the hazard and your injuries
- Medical records and bills
- Insurance correspondence
- Witness contact information
- Proof of missed work
Don't alter evidence, post details on social media, or contact witnesses in a way that could be seen as pressuring them.
Common Issues and When a Claim May Not Succeed
Slipping on someone else's floor doesn't automatically mean they owe you money. You still have to prove duty, breach, causation, and damages. Common weaknesses that sink otherwise sympathetic claims include:
- No photos or documentation of the hazard itself
- No record of the hazard before it was cleaned up
- No proof of how long the condition existed
- Delayed or inconsistent medical treatment
- Pre-existing conditions overlapping the claimed injury
- Missed filing deadline
Some situations fall outside standard premises liability entirely:
- Workplace injuries usually go through workers' compensation regardless of fault
- Government-owned property often involves capped damages and shortened notice windows
- A defective product that caused the fall, like a broken step or faulty ladder, may support a product liability claim against the manufacturer instead of the property owner
One more warning: don't sign a release or accept a quick offer before you understand your medical prognosis. Once you sign, the claim is typically over, even if your symptoms worsen or you need additional treatment later.
Conclusion
Slip and fall settlements come down to two things: provable liability and the documented impact of your injury. There's no national average that predicts what your claim is worth, and no formula that skips the work of building evidence.
What consistently strengthens a claim:
- Getting medical care immediately and following through on treatment
- Preserving evidence before it disappears
- Confirming Florida's current deadlines and comparative-fault rules apply to your situation
- Reading any offer against your likely net recovery, not just the headline number
If you were hurt on someone else's property in Florida, Olowu Law, P.A. offers a free, no-pressure case review.
Michael Olowu built his practice after years spent on both sides of the courtroom, prosecuting cases and defending insurers, and now applies that perspective to injured clients across Broward, Miami-Dade, Palm Beach, and Monroe counties.
A free consultation doesn't guarantee any particular result, and nothing here should be treated as legal advice for your specific situation.
Frequently Asked Questions
What is the typical payout for a slip and fall?
Payouts vary enormously based on injury severity, proof of liability, documented damages, insurance limits, and comparative fault. There's no reliable "average" that predicts an individual claim's value.
What is a good settlement offer for a slip and fall?
Compare any offer against your documented past and future losses, pain and suffering, likely deductions, and evidence strength, not just the dollar figure alone. An offer ignoring future medical needs is rarely a good one.
Can you get compensation for a slip and fall?
Yes, if you can show a responsible party owed you a duty of care, breached it through a dangerous condition, and that breach caused injuries with documented damages. Specific requirements depend on your state's law.
How long does a slip and fall lawsuit usually take?
Timing depends on your medical recovery, how contested liability is, and whether the case settles before or after a lawsuit is filed. A pre-suit settlement can resolve in months; a litigated, disputed case often takes much longer.
Do I pay taxes on personal injury settlement money?
Compensation for physical injuries is generally not taxable, but punitive damages and interest usually are, according to IRS Publication 4345. Talk to a tax professional about how your specific settlement is allocated.
What are the four proofs of negligence?
Duty, breach, causation, and damages. The exact legal standards and available defenses for each element depend on the state law governing your claim.